The $25,000 Form 5472 penalty, in plain words
What the IRS instructions say about Form 5472 penalties, when more penalties apply, and the mistakes behind them. Every rule links to the source.

By Thibault Chassagnol, founder of 5472Direct
Published Updated
Checked against the IRS Instructions for Form 5472 (Rev. 12/2024).
What the IRS instructions say
Four rules worth knowing before the deadline, quoted in plain words.
$25,000 per form, per year
The IRS can assess a $25,000 penalty for each Form 5472 that is not filed when due and in the way the instructions prescribe. The same penalty applies for failing to keep the required records. (IRC Section 6038A(d).)
Incomplete counts as not filed
The instructions are explicit: filing a substantially incomplete Form 5472 is a failure to file Form 5472.
$25,000 more, every 30 days
If the failure continues for more than 90 days after the IRS notifies you, an additional $25,000 applies per related party for each 30-day period, or part of one, after that.
Criminal penalties exist too
Sections 7203, 7206 and 7207 of the tax code can apply to failing to submit information, or to filing false or fraudulent information.
Source: IRS instructions for Form 5472 and IRC Section 6038A.
Five mistakes behind most penalties
Each of these is avoidable once you know it exists.
Missing the deadline
Form 5472 is due with the pro forma 1120 — usually April 15 for a calendar-year LLC. A Form 7004, filed by that date, moves the deadline to October 15.
Thinking “no revenue” means “nothing to report”
The instructions’ Part V list includes contributions to the LLC and distributions from it, not just revenue. If you’re unsure whether an amount belongs on the form, ask a tax professional.
Leaving the form substantially incomplete
Missing owner details, missing transactions, or no attached statement describing the year’s reportable transactions can count as not filing at all.
Sending it the wrong way
Foreign-owned U.S. DEs cannot e-file. The packet goes by fax to 855-887-7737 or by mail to the IRS PIN Unit in Ogden, Utah, with “Foreign-owned U.S. DE” written across the top of the 1120.
Changing the reference ID
An owner without a U.S. tax ID is identified by a reference ID number. The instructions require using the same one consistently, every year.
Source: IRS instructions for Form 5472.
What 5472Direct does about it
Our software fills in the forms from the facts you give it. We don’t decide what belongs in your filing, and we don’t promise outcomes — but the process is built around these mistakes.
The eligibility check comes first
Fourteen yes/no questions before you pay. Complex cases are told up front and referred to a CPA partner.
Filled from your answers
Fixed rules, not AI, fill the forms. Imported transactions come with suggested categories. You review them and can change any of them. The final categories are your decision.
The right delivery route
With IRS Direct Delivery, we fax your signed packet to the IRS’s dedicated fax number and email you the transmission receipt — evidence the fax was sent, not that the IRS accepted it.
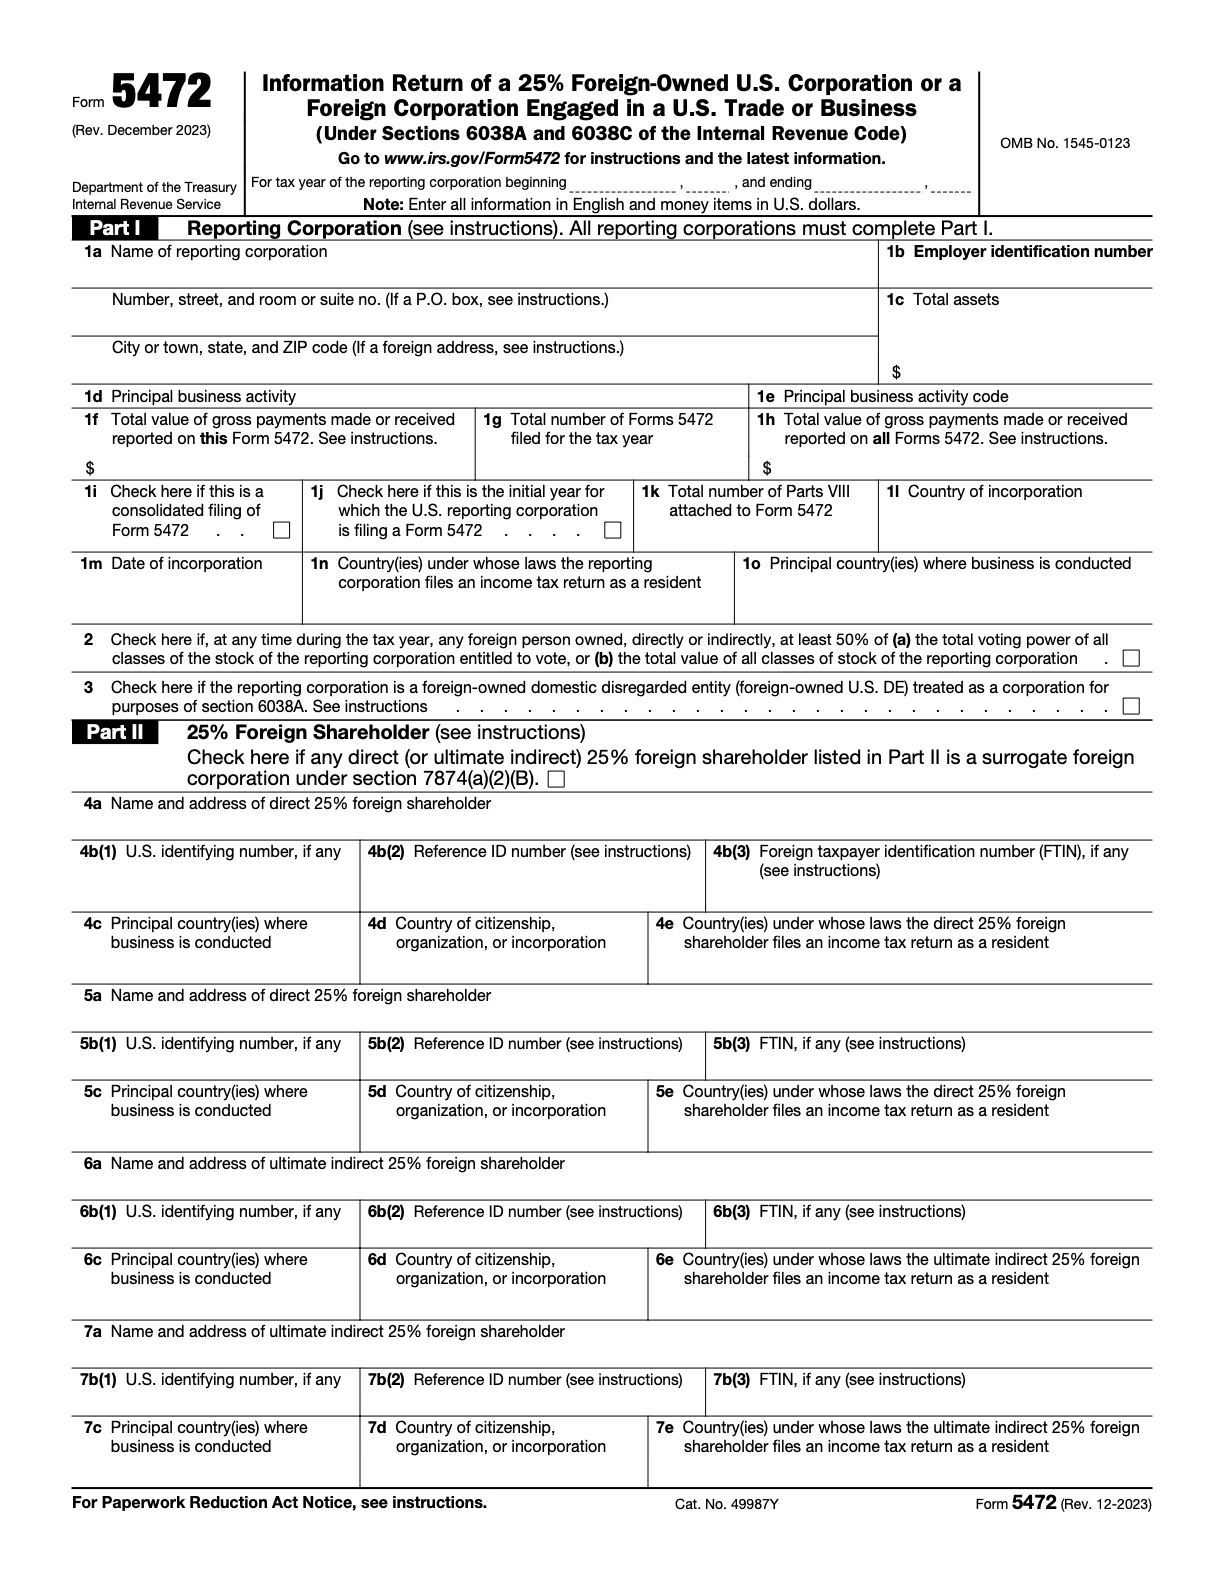
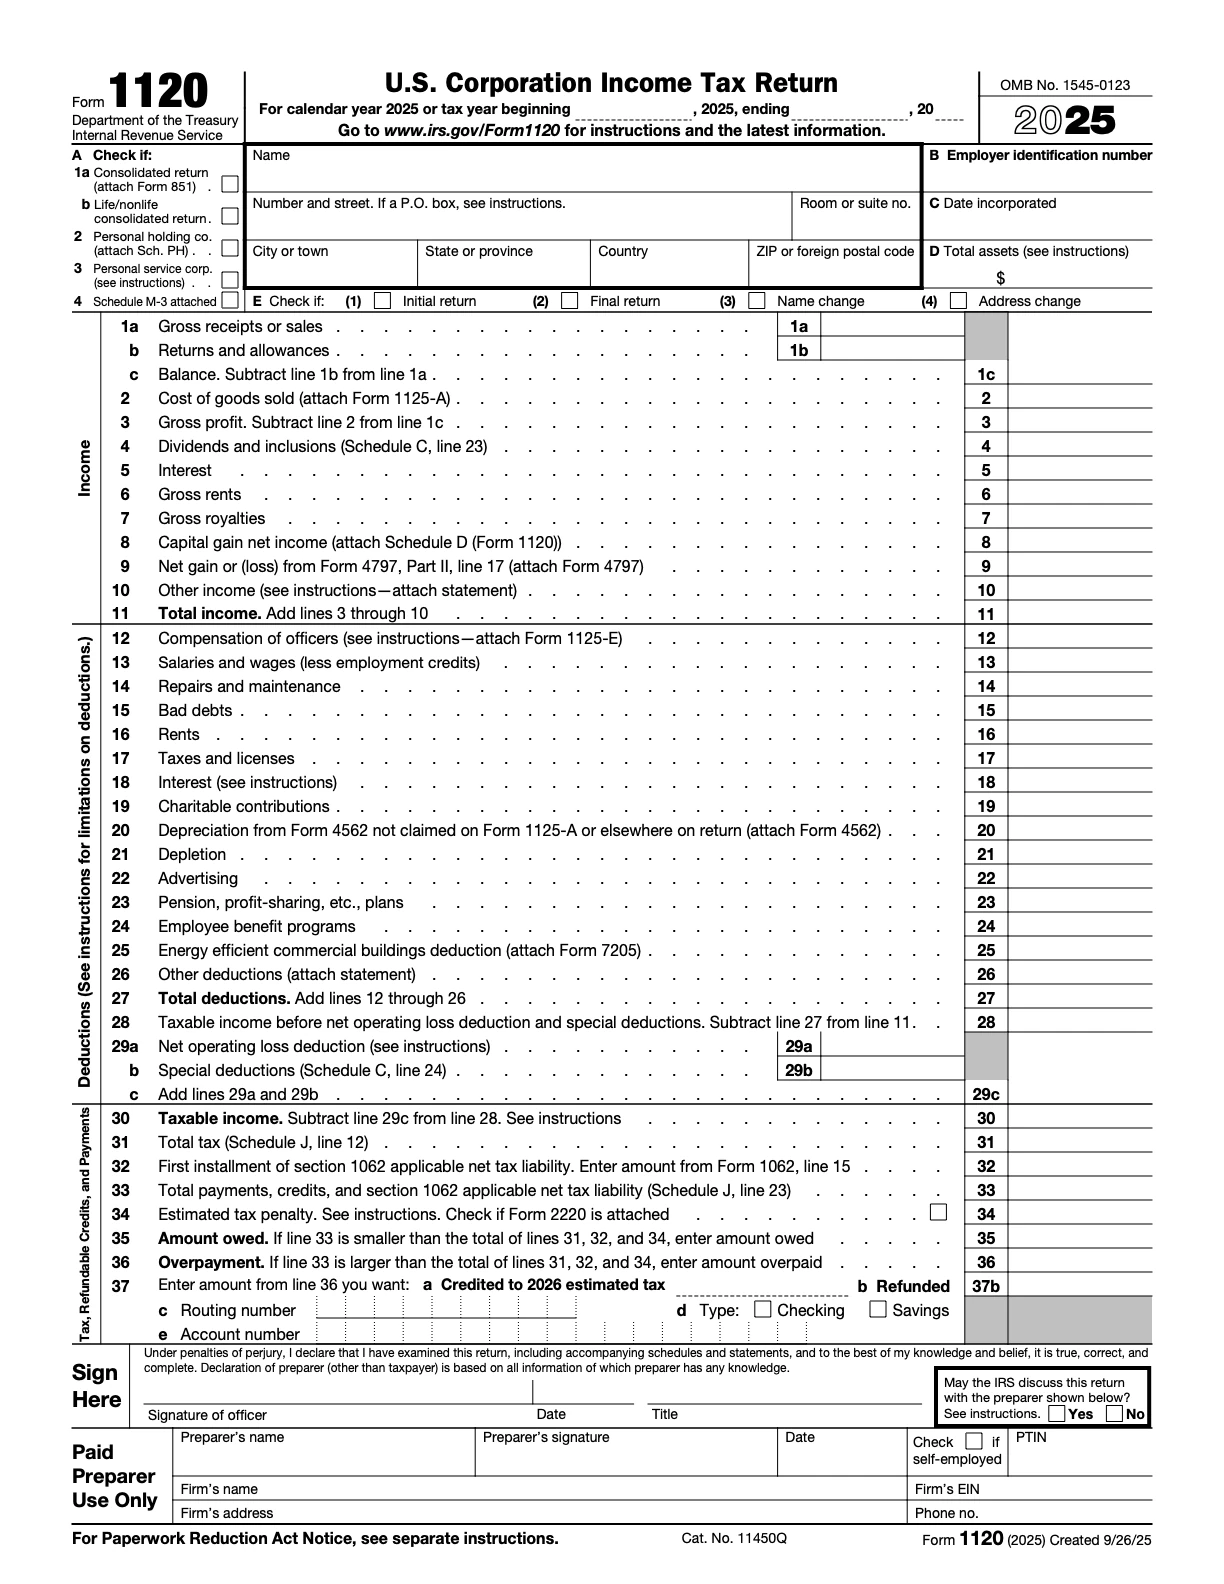
Still need to file Form 5472 for tax year 2025?
Check if your LLC qualifies for free, then get your IRS-ready filing in the same session.